How Much Should I Put Aside for Tax? A Practical Cash-Flow Guide for Business Owners
How to build a tax reserve for income tax, GST, PAYG withholding and super without relying on a misleading one-size-fits-all percentage
A healthy bank balance can create a false sense of comfort.
A business owner sees cash available, pays suppliers, makes drawings or approves a new purchase, then receives a BAS or income-tax bill that feels unexpectedly large.
Yet part of the bank balance may already represent GST collected from customers, tax withheld from employees, unpaid superannuation or income tax that has not yet fallen due.
The question is not simply how much cash the business has. It is how much remains after allowing for obligations the business has already created.
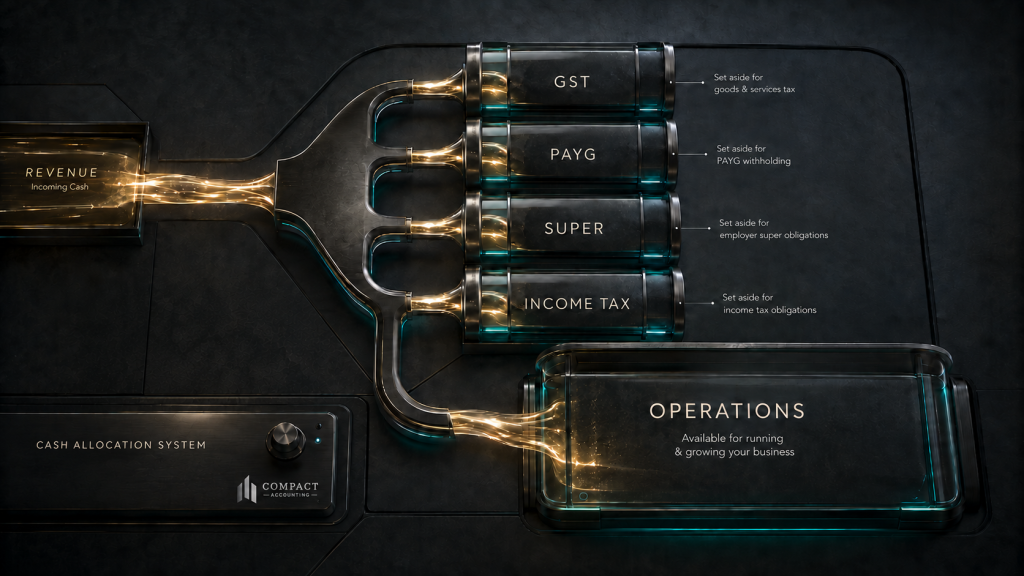
Money in the business bank account is not necessarily money available to spend.
This is particularly important for people moving from employment into business. Tax is usually withheld from wages before the balance reaches an employee. In business, the gross receipt often arrives first and the tax obligation follows later.
So, what percentage of every payment should you put aside?
The honest answer is that there is no reliable percentage that suits every business. A better approach is to separate the different obligations, estimate the likely income-tax position and turn the result into a repeatable reserve process.
| Important: The percentages and examples in this Resource are general cash-flow illustrations only. They are not a recommendation that any particular business should retain a specific percentage of receipts. The appropriate reserve depends on factors including business structure, taxable profit, GST, PAYG instalments, payroll obligations, losses, drawings, other income and timing. Businesses should obtain advice based on their own circumstances before relying on any percentage or rule of thumb. |
Why 20%, 30% or “one-third” may all be wrong
Rules such as “save 20% of everything” or “put aside one-third” can be useful as an initial discipline. They can also be excessive for one business and dangerously low for another.
Consider two businesses that each receive $220,000 including GST during the year. One is a consultant with relatively low overheads and a strong profit margin. The other buys substantial materials and employs staff. The same percentage of receipts could materially understate the first business’s income-tax reserve and overstate the second’s.
Income tax is generally driven by taxable profit, not simply the amount passing through the bank account. The result can also be affected by the structure, other income, deductions, losses, capital gains and PAYG instalments already paid.
A percentage of gross receipts is simple, but it is only useful when tested against current figures.
| A useful reserve percentage is not necessarily the neatest number. It should be supported by the business’s current figures. |
Separate the obligations first
Business owners often use “tax” to describe several liabilities. Combining them into one unexplained figure makes it difficult to know whether enough has been reserved.
GST
For a GST-registered business, GST collected on taxable sales should not be treated as ordinary income available for spending. In a straightforward GST-inclusive taxable sale, one-eleventh of the price represents GST. However, the eventual BAS payment is not necessarily one-eleventh of total receipts because eligible GST credits, GST-free or input-taxed supplies, adjustments and other BAS items may change the result.
Transferring one-eleventh of each receipt may be a conservative administrative starting point for a simple business making fully taxable sales. It is not a universal GST calculation.
PAYG withholding
PAYG withholding is tax withheld from payments such as employee wages and remitted to the ATO. It is different from PAYG instalments. Once an amount has been withheld, absorbing it into everyday operating cash creates a future shortfall rather than a saving.
Employee superannuation
Superannuation is another employment cost that needs to be recognised when payroll is processed. Under Payday Super, which commenced on 1 July 2026, employers generally need contributions to reach an employee’s super fund within seven business days of the relevant payday. Exceptions and special timing rules can apply.
This shorter payment cycle reduces the usefulness of thinking about super as a distant quarterly bill. Payroll, cash-flow planning and the timing of the actual transfer now need to work together.
PAYG instalments
PAYG instalments are regular prepayments towards the expected income tax on business and investment income. The amounts paid are credited when the relevant income-tax return is assessed.
They help spread tax across the year, but do not guarantee that the final assessment will be fully covered. The return may still produce an amount payable, a refund or no further amount.
Other obligations
The reserve may also need to allow for payroll tax, fringe benefits tax, workers compensation adjustments, licences or industry-specific charges. Identify these separately rather than hiding them inside a general percentage.
Separate the obligations first. Estimate the percentage second.
Turnover, profit and cash are three different things
Turnover is the revenue generated by the business. Taxable profit broadly starts with assessable income less allowable deductions, then incorporates any relevant tax adjustments. Cash is simply what has moved into and out of the bank account.
The three figures rarely move in perfect alignment.
A profitable business may have limited cash because customers have not paid, stock or equipment has been purchased, loan principal has been repaid, owners have made drawings or the business is funding growth. Those outflows may not reduce taxable profit by the same amount or at the same time.
Conversely, a business may temporarily hold substantial cash that is not profit. The balance could include GST, PAYG withholding, customer deposits, borrowed funds, unpaid supplier amounts or money reserved for tax.
A profit-and-loss report helps explain performance. A cash-flow forecast helps show whether money is likely to be available when wages, suppliers, tax and other obligations fall due. Both are needed.
Building a tax-reserve system
A workable reserve process need not be complicated, but it should be based on reliable information.
1. Identify each obligation
List the categories that apply: GST, PAYG withholding, superannuation, PAYG instalments, expected year-end income tax and other known liabilities. If one bank account holds them all, keep a schedule showing each component.
2. Bring the bookkeeping up to date
The calculation is only as reliable as the records beneath it. Sales and expenses need recording, bank accounts reconciling, payroll processing, GST coding reviewing and private or capital transactions identifying.
Books that are several months behind can make both profit and the apparent tax reserve misleading.
3. Forecast taxable profit
Start with year-to-date results and estimate the rest of the financial year. Consider contracts, seasonal patterns, staffing, expenses, asset purchases, one-off income, capital gains, prior losses and tax adjustments.
Accounting profit is a starting point, not always the final taxable figure.
4. Estimate the tax position for the correct structure
The estimate may involve individual rates, company tax, partnership or trust allocations, other income, tax offsets, PAYG instalment credits and company extraction consequences.
This is where a copied percentage commonly breaks down: it may reflect someone else’s structure and circumstances rather than yours.
5. Compare the forecast with amounts already paid or reserved
Deduct PAYG instalments already paid and identify amounts held for GST, withholding, super and income tax. Do not count the same balance twice because several liabilities share an account.
6. Convert the shortfall into regular transfers
Divide the remaining forecast obligation across the weeks, fortnights or months before payment is expected. The transfer can then be treated as a normal operating commitment rather than an optional payment made only when cash feels plentiful.
A consultant who transfers 25% of each GST-inclusive receipt has created a useful habit. However, it mixes GST and income tax and may not reflect expenses, other income or PAYG instalments. It must be tested—not assumed sufficient.
7. Review and adjust
Quarterly review may suit a stable business. Monthly review may be better where revenue grows quickly, margins fluctuate, large contracts arise or cash flow is tight.
Many businesses benefit from a combined approach: reserve transaction-based amounts such as GST and PAYG withholding, then add a forecast-based income-tax reserve.
Does the business structure change the reserve?
Yes. The legal and tax structure changes both who may pay the tax and what else needs to be considered.
For a sole trader, business profit is generally included in the owner’s individual tax position alongside relevant outside income, deductions and tax factors. Drawings are neither the basis of the tax calculation nor a wage paid to the sole trader.
For a partnership, the tax result is generally allocated between the partners. Each may need a different reserve based on their share and wider personal position. Retaining the cash does not necessarily prevent tax on that share.
For a company, the company is a separate taxpayer, but company income tax is not the whole cash plan. GST, PAYG instalments, remuneration, withholding, super, fringe benefits, dividends and shareholder loan accounts may also matter. Money left after company tax cannot automatically be withdrawn personally without further consequences.
For a trust, the outcome can depend on the deed, income concepts, beneficiary entitlements, trustee resolutions and distributions. Its bank balance is not a reliable measure of beneficiaries’ tax.
PAYG instalments help, but can lag behind growth
The ATO generally works out PAYG instalment amounts or rates using information from a recent tax return. That means the instalments may not perfectly reflect what is happening now.
If a company’s profit rises sharply after its latest return, current instalments may cover only part of the eventual tax. It should forecast and reserve the difference.
Where circumstances change, a taxpayer may be able to vary PAYG instalments. Any variation should be based on current accounts and a supportable forecast. If varied instalments are too low compared with the eventual tax on instalment income, general interest charge may apply.
Most importantly, reducing an instalment improves immediate cash flow but does not reduce the tax created by the year’s actual taxable income.
| Varying an instalment changes the timing of payments. It does not rewrite taxable profit. |
Plan through the summer squeeze and not just to Christmas
November to February can combine closures, leave and holiday pay, reduced invoicing, slower customer payments, renewals, stock purchases and personal drawings. Wages, rent, loans and tax continue even when trading slows.
A seasonal business might invoice strongly before Christmas but receive much of that cash in late January. December sales are of limited help if January’s wages and rent fall due before customers pay.
For quarterly reporters, the October-to-December activity statement is generally due on 28 February, although an agent or another applicable concession may change the date. By November, a useful forecast should therefore extend at least to the end of February, not merely to the Christmas shutdown.
Before large drawings, bonuses, asset purchases or discretionary payments, check the cash position after summer costs and statutory obligations.
A separate account helps but it does not do the calculation
A dedicated tax account can improve visibility, reduce temptation and simplify BAS and tax planning. Official guidance also encourages businesses to set money aside regularly, including keeping amounts such as GST separate from day-to-day cash flow.
The balance must still be reconciled to actual liabilities. One account may contain several categories, and a fixed transfer does not prove the reserve is correct. Nor does a separate account make the money legally protected.
| A separate account creates discipline. It does not replace a tax forecast. |
Warning signs that the reserve needs attention
The system may not be working if:
- BAS payments are repeatedly late;
- PAYG withholding or super is being used for general operating costs;
- the tax account is emptied between lodgments;
- bookkeeping is months behind;
- owner drawings are based only on the bank balance;
- the reserve percentage has not changed despite rapid growth;
- PAYG instalments are reduced without a current forecast;
- new debt is regularly needed to pay recurring tax; or
- no one can explain what the tax-account balance is intended to cover.
These signs do not all mean the same thing, but recurring difficulty meeting debts calls for prompt attention.
If the reserve is already too low, bring the records up to date and quantify GST, withholding, super and income tax separately. Prepare a short-term cash-flow forecast, review drawings and discretionary spending, and lodge required statements and returns on time even if full payment may be difficult. Contact the ATO or other relevant authority early and obtain advice before varying instalments, refinancing or entering a payment arrangement.
Concern about the ability to pay debts as they fall due may also require legal or insolvency advice. A tax-reserve article is not a substitute for reviewing the business’s position.
Tax reserve checklist
- Which tax and employee obligations apply to the business?
- Which amounts are collected or withheld for later payment?
- Are the accounts current and reconciled?
- What is the forecast taxable profit for the year?
- What PAYG instalments have already been paid?
- Are GST, PAYG withholding, super and income tax tracked separately?
- Does the estimate reflect the correct business structure and relevant owner or beneficiary circumstances?
- Have seasonal trading, holidays and payment delays been forecast?
- Is reserved cash separated from day-to-day operating cash?
- How often will the estimate be recalculated?
- What upcoming transaction could materially change the result?
- Are drawings or discretionary payments being made before statutory obligations are protected?
- Is advice required before varying instalments or making a major distribution?
A useful percentage may emerge from this process and can then be automated. But it should remain connected to actual results and a current forecast.
A tax reserve is a living forecast, not a percentage selected once and forgotten.
How Compact Accounting can help
Unsure whether your current tax reserve reflects the way your business is actually performing? Compact Accounting can help review your current accounts, forecast likely taxation and statutory obligations, and develop a reserve process for the months ahead.
Where legal, insolvency, lending or financial-product advice is required, assistance should be obtained from an appropriately qualified adviser.
General Information Only
This Resource contains general information only and does not take into account your objectives, financial situation or particular circumstances. It is not personal tax, legal, financial-product, lending or insolvency advice. Tax outcomes and payment obligations depend on the applicable facts and law, which may change. Obtain appropriately qualified advice before acting or deciding not to act.
Reading this resource or contacting Compact Accounting does not, by itself, create an accountant-client relationship. Any engagement is subject to our written acceptance and agreed scope of services.
Liability limited by a scheme approved under Professional Standards Legislation.
References & Further Reading
- ATO PAYG instalments
- ATO How we calculate your PAYG instalment amount or rate
- ATO How to vary your PAYG instalments
- ATO Accounting for GST in your business
- ATO BAS and GST tips
- ATO Activity statement due dates
- ATO PAYG withholding
- ATO About Payday Super
- ATO Payment deadlines for Payday Super
- ATO Using business money and assets for private purposes
- ATO Managing payments
- business.gov.au: Guide to managing cash flow
- business.gov.au: Set up a cash-flow statement
- business.gov.au: Create a budget
Last Reviewed: 28 October 2026